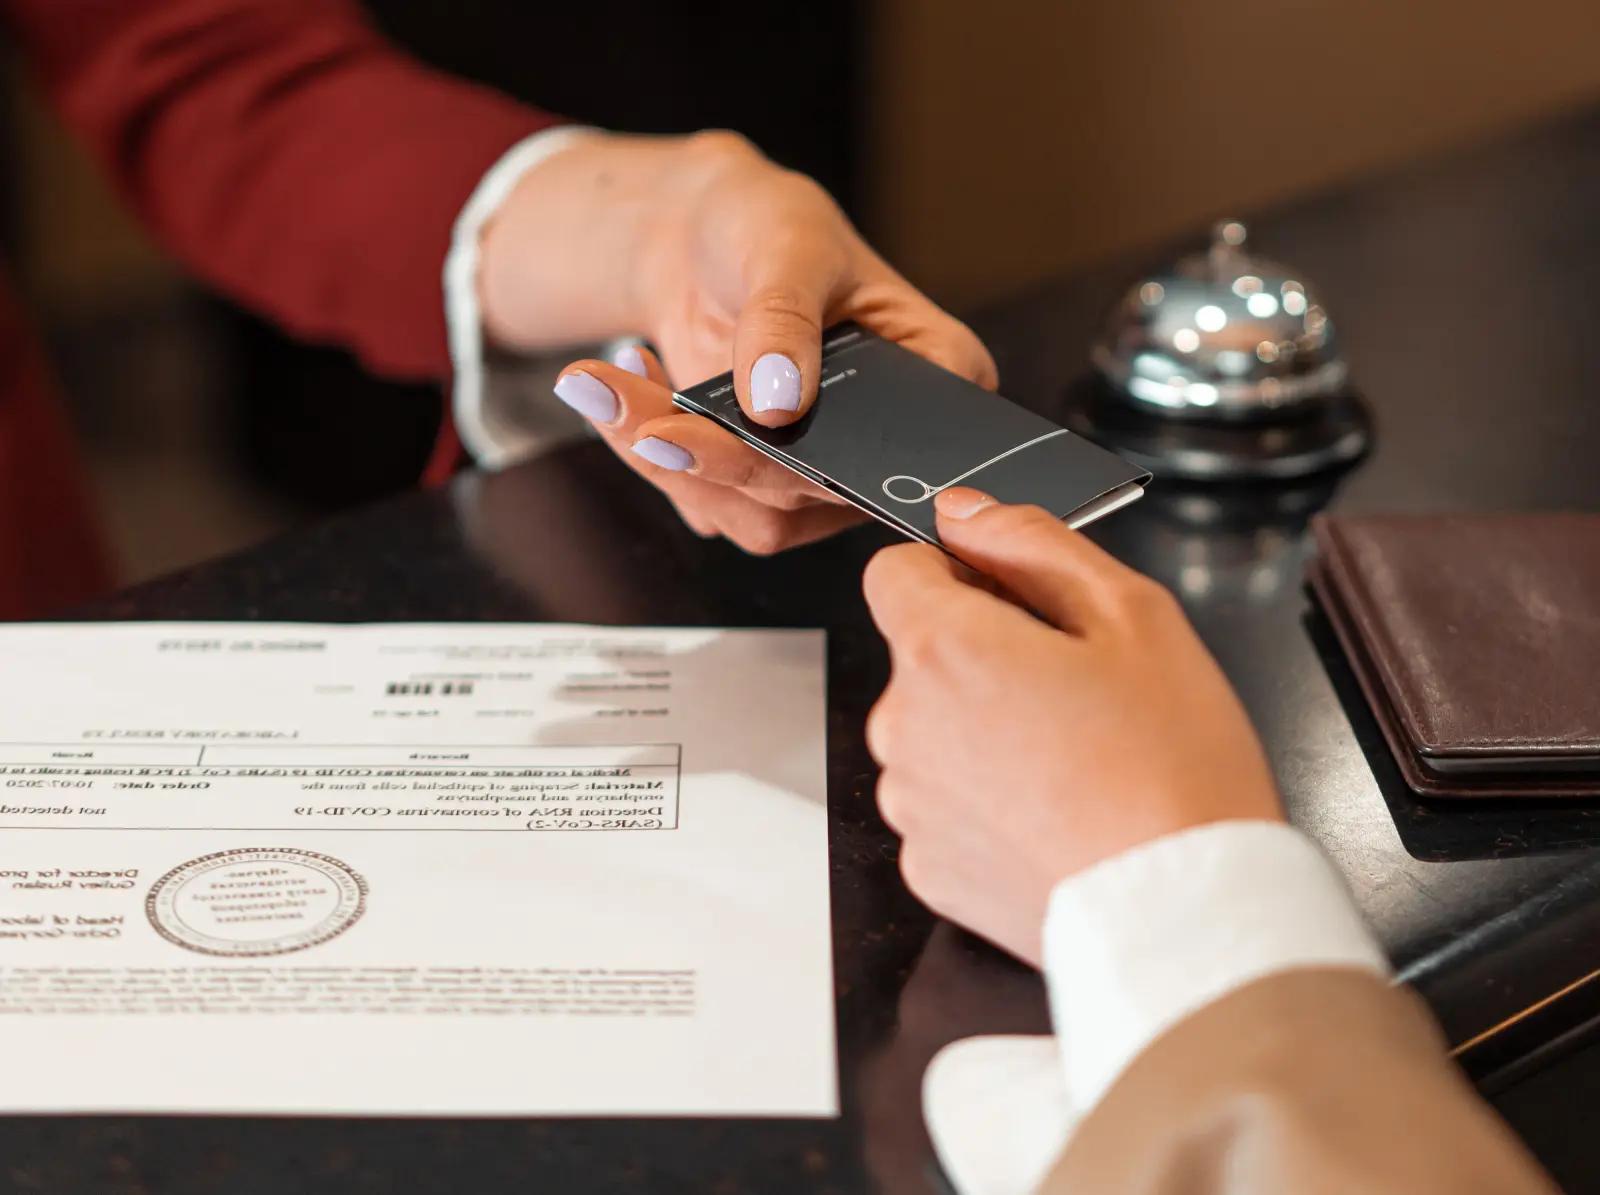
Your hotel is already paid.
You arrive at reception, hand over your passport and hear:
“We just need a card for incidentals.”
No problem.
You tap your debit card.
A few minutes later, €300, €500 or even more appears to be missing from your available balance.
You did not spend it.
The hotel did not necessarily charge it.
The money is simply unavailable.
Welcome to the hotel authorization hold.
And if you are travelling with a debit card and a limited amount of cash in your bank account, this seemingly harmless check-in procedure can create a surprisingly serious problem.
A hotel deposit is not always a charge
Hotels commonly place an authorization hold on a payment card at check-in.
It can cover things such as:
- room and taxes
- minibar
- food and drinks
- parking
- room service
- damage
- other incidental expenses
Marriott’s current digital-entry terms say that at check-in the issuing bank may place a hold covering room and tax, applicable resort fees and an additional amount for incidentals.
Hilton similarly explains that even guests who have already prepaid their stay may still have a card hold placed for incidentals at check-in.
That distinction is important.
You can have:
HOTEL ROOM
Already paid: €700

AND

CHECK-IN HOLD
Temporarily reserved: €300
Your hotel did not suddenly become €1,000.
But for a period of time, you may need access to €1,000 of financial capacity.
Why debit cards create the bigger problem
An authorization can happen on both credit and debit cards.
The practical difference is where the hold lands.
Credit card
A €400 authorization generally reduces your available credit.
Example:
Credit limit:       €4,000
Hotel hold:           €400

Available credit:   €3,600
Your current-account cash has not disappeared.
Debit card
The same hold can affect money directly associated with your bank account.
Example:
Account balance:    €1,200
Hotel hold:           €400

Available funds:      €800
You still technically have the money.
But you may not be able to spend it.
Some Hyatt properties state this extremely clearly in their policies: debit-card authorization funds are shown as pending and therefore become unavailable to the guest. Some also recommend using a credit card at check-in and a debit card to settle the final balance at checkout.
That is the travel trick.
The problem is often not the cost of the hotel. It is temporary access to your own money.
The €500 example
Imagine a five-night holiday.
You prepaid:
Hotel: €750So you arrive with:
Bank account: €1,500You expect the €1,500 to cover:
Restaurants
Transport
Shopping
Activities
Emergency money
At check-in, the hotel authorizes:
€100 per night
×
5 nights
=
€500
Your available cash can suddenly become:
€1,500
-
€500
=
€1,000
Nothing has actually been purchased with that €500.
But for practical purposes during the holiday:
You cannot use it.That is a very different problem from a €500 expense.
The hold may survive your checkout
Here is where many travellers become confused.
You check out.
The receptionist tells you:
“We have released the deposit.”
You check your banking app.
The money is still unavailable.
Both statements can be true.
The hotel can release the authorization from its side, but your issuing bank may need additional time before the funds become available again.
Marriott currently says its check-in hold may remain until the issuing bank releases it, with its digital-entry terms referring to up to five business days after departure.
IHG says that for a card linked to a bank or checking account, held funds may remain unavailable for at least 72 hours after checkout or longer depending on the financial institution.
Hilton says its hold is generally released after checkout within 72 hours, while noting that the card provider may take longer.
And some Hyatt properties warn debit-card customers that released authorizations may take 7–10 business days, potentially longer depending on the bank.
So:
Hotel releases hold
≠
Money immediately available
The road-trip problem is even worse
Imagine a ten-day trip:
Hotel A: 3 nights
Hotel B: 3 nights
Hotel C: 4 nights
Each places approximately:
€250 holdYou leave Hotel A.
Its €250 has not yet returned.
You check into Hotel B.
Another:
€250gets blocked.
Then you reach Hotel C before the first authorization has completely disappeared.
In the wrong timing scenario, you might temporarily have:
Hotel A: €250
Hotel B: €250
Hotel C: €250

TOTAL:
€750
tied up.
Again:
You have not spent €750.
But you may temporarily be unable to use it.
For someone travelling with €1,500–€2,000 in their main account, that matters.
Prepaid hotel does not automatically solve it
This is probably the biggest misconception.
You show reception:
“But I already paid for the hotel.”
That does not necessarily eliminate the incidental hold.
Hilton’s current FAQ specifically addresses this situation: even when accommodation has been prepaid, a hotel may still require a card at check-in and place a hold for incidentals such as food, drink, parking and other charges.
Think of them as two separate things:
ROOM PAYMENT
=
What you owe for accommodation

INCIDENTAL AUTHORIZATION
=
Security against additional spending
Paying one does not automatically eliminate the other.
The question to ask BEFORE handing over your card
Instead of simply asking:
“Do you need my card?”
ask:
“How much will you authorize on the card?”
That one sentence can save a lot of confusion.
Even better:
“Is the authorization per night or per stay?”
Because these two policies are very different.
Example A:
€50 per stay
=
€50
Example B:
€50 per night
×
7 nights
=
€350
You want to know that before tapping the card.
Ask how long the release normally takes
Second question:
“When you release the authorization at checkout, how long can it remain pending?”
The hotel cannot guarantee your bank’s processing time.
But it can explain its own procedure.
Now you know whether you are potentially dealing with:
hoursor:
several business daysThat becomes especially important if another hotel, rental-car company or cruise line will require a deposit immediately afterwards.
Rental cars can create the same problem
Hotels are not the only travel businesses using deposits.
Rental-car companies can require much larger authorization amounts.
For example, Enterprise’s current Skopje Airport terms list security deposits ranging from €290 to €1,000 depending on vehicle category, and state that the deposit there must be provided using a valid credit card.
So imagine the combination:
Hotel hold:       €400
Rental car hold:  €390

TOTAL CAPACITY:
€790
before you have bought lunch.
This is why payment-card planning should be part of trip planning.
Not something you think about while standing at reception.
The Fintayo two-card travel setup
A practical setup is:
Card 1 — check-in / deposits
Preferably a suitable credit card with enough available limit, where accepted.
Use it for:
Hotel authorization
Rental-car deposit
Other security holds
Card 2 — daily spending
Use another card for:
Food
Transport
Shopping
Tickets
Cash withdrawals
Why?
Because if one card accumulates large pending authorizations, you still have a separate source of everyday spending capacity.
It also gives you redundancy if:
A card is declined
A card is lost
A bank fraud system blocks it
A terminal does not accept that card
But do not blindly use a credit card
There is an important qualification.
A credit card is useful only if:
The hotel accepts it
You have sufficient available limit
You understand its fees
You can pay the balance responsibly
A €500 hold on a card with only:
€700 available limitstill creates a problem.
After authorization:
€200 availableThe issue has simply moved from your bank balance to your credit limit.
The Fintayo rule is therefore not:
Credit cards are always better.
It is:
Do not use the account containing your day-to-day travel cash for a large authorization unless you understand the consequences.
Do not use your only card
This is one of the simplest travel mistakes to avoid.
You travel with:
One debit cardIt contains:
All holiday moneyThen:
Hotel freezes part of itand later:
Bank blocks a suspicious transactionNow you have one problem and no backup.
For international trips, two independent payment methods are far safer than one.
Ideally, do not keep both in the same wallet.
The checkout trick
Some hotel policies explicitly recommend a useful strategy:
Credit card
→ authorization at check-in

Debit card
→ final payment at checkout
Some Hyatt properties currently make exactly this recommendation to debit-card users.
Why can this work?
The credit card absorbs the temporary hold.
At checkout, you tell reception:
“I’d like to settle the final bill with this debit card.”
The hotel processes the actual bill.
The authorization on the credit card is released according to the hotel’s and issuer’s process.
Your checking-account funds were not tied up for the entire stay.
But always confirm the property allows changing the payment method at checkout.
Photograph or keep the final hotel bill
Do not walk away with nothing.
Ask for the final folio or invoice showing:
Room
Taxes
Extras
Final payment
Balance due: 0
If the authorization remains pending for an unusually long period, you now have documentation showing the stay was settled.
Marriott advises guests with billing discrepancies to contact the property and retain updated hotel-bill documentation when corrections are made.
That is far more useful than telling your bank:
“The receptionist said everything was fine.”
The Fintayo check-in script
At reception, ask:
Before I provide the card,
how much will you authorize?
Then:
Is that amount per night
or for the entire stay?
Then:
When you release it,
how long can it remain pending?
And if you have both debit and credit cards:
Can I use this card for the authorization
and another card for the final bill?
Four questions.
Thirty seconds.
Potentially hundreds of euros of liquidity protected.
The €1,000 holiday cash-flow test
Before travelling, calculate:
Available trip money:
€________

Hotel authorization:
€________

Rental-car deposit:
€________

Other deposits:
€________

TOTAL TEMPORARILY UNAVAILABLE:
€________
Then:
Available trip money
-
temporary holds
=
money actually available to spend
Example:
Bank balance:          €2,000

Hotel hold:              €400
Rental car:              €390

Actually accessible:
€1,210
That is the number you should build the trip around.
Not €2,000.
Do this before a long trip
If the hotel website does not clearly publish its authorization policy, send a message before travelling:
“Could you confirm the card authorization/deposit required at check-in, whether it is per night or per stay, and the usual release process after checkout?”
This matters particularly for:
- expensive resorts
- long stays
- multiple hotels
- car rentals
- cruises
- travellers relying primarily on debit cards
- trips where your bank balance is close to your planned budget
The Fintayo takeaway
A hotel authorization hold is not necessarily a hidden fee.
It is a cash-flow problem.
And on a debit card, cash flow matters because the hold can make real money in your account temporarily unavailable.
So before hotel check-in, remember:
Ask the hold amount.
Ask whether it is per night.
Ask how release works.
Keep daily spending money separate.
Carry a backup payment method.
The hotel room may already be paid.
Your account can still lose access to hundreds for several days.
And discovering that while standing in another country with dinner, transport and the rest of the trip still ahead is a travel trick worth avoiding.