For years, many people felt pressure to spend money they didn’t really want to spend.
Whether it was agreeing to expensive dinners, booking costly vacations with friends or buying the latest gadgets simply to fit in, saying “I can’t afford it” often felt uncomfortable.
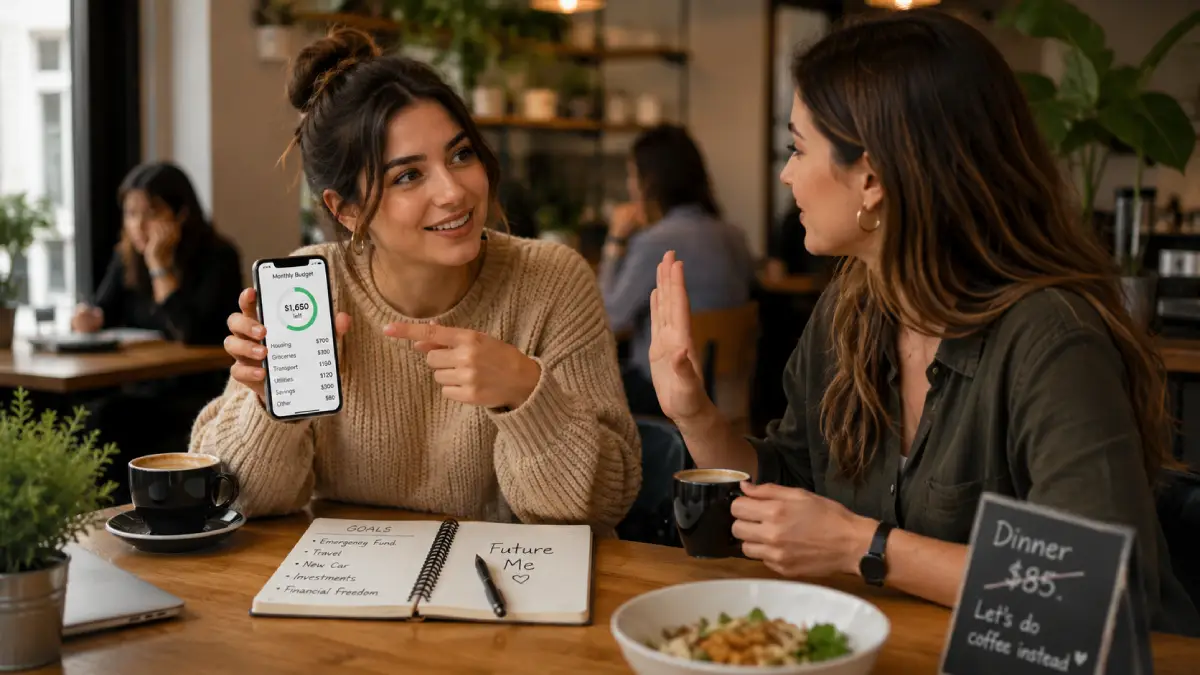
A growing personal finance trend known as “loud budgeting” is trying to change that.
Instead of quietly overspending or making excuses, more people—particularly younger adults—are openly talking about their financial goals and explaining why certain purchases simply don’t fit their budget.
What is loud budgeting?
Loud budgeting is the practice of being honest about your financial boundaries.
Rather than pretending you’re busy or inventing another excuse, the idea is to simply say:
“I’m saving for a house.”
“That isn’t in my budget this month.”
“I’d rather keep that money invested.”
“Let’s do something less expensive instead.”
The goal isn’t to avoid social activities.
It’s to remove the embarrassment that often comes with saying no to unnecessary spending.
Why the trend is growing
The concept has gained popularity as higher living costs continue to pressure household budgets.
Inflation, expensive housing and elevated borrowing costs have forced many consumers to become more intentional with their money. At the same time, social media has made it easier to compare lifestyles, increasing the pressure to spend.
According to a recent Bank of America report cited by Reuters, 42% of Gen Z adults say they practice loud budgeting, while 75% actively look for ways to save money when making social plans.
Financial advisers say the approach can reduce impulsive spending and make long-term goals easier to achieve.
Why it works
One of the biggest reasons people overspend isn’t poor budgeting.
It’s social pressure.
Many purchases happen because people don’t want to disappoint friends, appear cheap or feel left out.
By being transparent about financial priorities, loud budgeting removes much of that pressure.
Instead of saying:
“Maybe next time.”
People simply explain:
“I’m focusing on saving money right now.”
That honesty often encourages others to do the same.
Small decisions can have a big impact
Declining just one expensive activity each week can make a noticeable difference over time.
For example:
Weekly expense avoided
Annual savings
$25
$1,300
$50
$2,600
$100
$5,200
Those savings could help fund an emergency fund, pay down debt or increase retirement contributions.
Spending with intention
Loud budgeting doesn’t mean never enjoying your money.
Instead, it encourages spending on things that genuinely matter while cutting back on purchases driven by habit or social expectations.
Someone might happily spend money on travel while skipping expensive restaurant meals.
Another person may choose concerts over luxury clothing.
The key is making decisions based on personal priorities—not outside pressure.
Bottom line
Loud budgeting isn’t about saying no to everything.
It’s about saying yes to the financial future you want.
As living costs remain high, openly discussing financial boundaries is becoming less of a taboo and more of a practical way to avoid unnecessary debt and stay focused on long-term goals.
For many people, the simple act of saying, “That’s not in my budget,” may be one of the healthiest financial habits they develop this year.
Americans hoping for cheaper borrowing may need to wait longer.
Federal Reserve Governor Christopher Waller warned Monday that interest rates may need to rise again in the near term if upcoming inflation data shows that price pressures are remaining high or beginning to accelerate.
The warning marks an important shift in tone. For months, much of the discussion surrounding the Federal Reserve focused on when policymakers might begin cutting rates. Now, at least some officials are openly considering whether inflation could require another round of monetary tightening.
In a speech delivered on July 13, Waller said the economy had reached a critical point. While inflation could begin moving lower, he said there was also a realistic possibility that upcoming data would show prices remaining elevated or rising further. In that scenario, tighter monetary policy could be required.
For households, the message is straightforward: credit cards, auto loans, personal loans and mortgages may not become cheaper anytime soon.
Why the Fed is worried about inflation again
The Federal Reserve aims to keep inflation near 2% over the long term. However, inflation has remained above that target, even after a prolonged period of higher interest rates.
At its June meeting, the central bank said economic activity was continuing to expand at a solid pace, while inflation remained elevated partly because of supply shocks and higher energy costs. The Fed kept its benchmark interest rate in a range of 3.50% to 3.75%.
Waller highlighted persistent price growth in core services, an area that includes expenses such as housing, insurance and medical care. These categories are particularly important because service inflation can be more difficult to reverse than temporary increases in food or gasoline prices.
The next major test will come with the release of the June Consumer Price Index on July 14. The Bureau of Labor Statistics is scheduled to publish the report at 8:30 a.m. Eastern Time.
That report could influence expectations for the Federal Reserve’s next policy meeting, scheduled for July 28 and 29.
What higher interest rates would mean for borrowers
The Federal Reserve does not directly set consumer loan rates, but changes in its benchmark rate influence borrowing costs throughout the economy.
If the Fed raises rates—or simply keeps them elevated for longer—consumers could continue facing expensive financing.
Credit cards
Most credit cards have variable interest rates linked to the prime rate. When the Federal Reserve raises its benchmark rate, credit card annual percentage rates usually move higher as well.
That means borrowers who carry balances from month to month could pay more interest, even if they do not make any additional purchases.
For someone with a large revolving balance, a relatively small rate increase can add hundreds of dollars to the total repayment cost.
Personal loans
Personal loan rates are usually fixed after approval, so existing borrowers would generally not see their payments change.
New borrowers, however, could receive more expensive offers if market rates rise. Consumers with weaker credit profiles would likely feel the effect most strongly.
Auto loans
Higher rates increase the monthly cost of financing a vehicle.
Even when the price of the car remains unchanged, a higher interest rate can significantly increase both the monthly payment and the total amount paid over the life of the loan.
Mortgages
Mortgage rates do not follow the Federal Reserve’s benchmark rate directly. They are influenced by bond markets, inflation expectations and the broader economic outlook.
However, renewed concern about inflation can push long-term borrowing costs higher. This could keep mortgage affordability under pressure and make refinancing less attractive.
Savers may continue to benefit
Higher rates are painful for borrowers, but they can benefit people holding cash.
Banks and financial institutions often offer higher returns on savings products when market interest rates are elevated.
Consumers may continue to find competitive yields through:
high-yield savings accounts;
money market accounts;
certificates of deposit;
short-term Treasury securities.
Some high-yield savings accounts were offering annual percentage yields of up to approximately 4.50% in July, far above the national average offered by traditional savings accounts. Rates and conditions vary by institution, and depositors should verify balance requirements, fees and insurance coverage before opening an account.
For savers, the current environment creates an opportunity to earn more on emergency funds and short-term savings without taking stock-market risk.
What consumers should do now
A possible rate increase does not mean households need to make sudden financial decisions. However, it does make certain priorities more urgent.
Borrowers carrying credit card debt should consider paying down high-interest balances before rates potentially move higher. Transferring debt to a lower-rate product may help, but fees and promotional deadlines need to be reviewed carefully.
Anyone planning to take out a mortgage, auto loan or personal loan should compare offers from several lenders. A difference of one percentage point can have a meaningful impact on a large or long-term loan.
Savers should review the rate currently paid on their accounts. Money left in a traditional account earning a very low yield may be losing purchasing power after inflation.
Consumers should also avoid assuming that rate cuts are guaranteed. The latest Federal Reserve comments show that monetary policy can change quickly when inflation data changes.
Why the next inflation report matters
The upcoming CPI report will provide a clearer picture of whether recent price increases are easing or becoming more entrenched.
May data showed consumer prices running 4.2% higher than one year earlier, according to the Bureau of Labor Statistics. Core categories remained an important source of pressure.
One softer report would not necessarily lead to immediate rate cuts. Likewise, one stronger report would not automatically produce a rate increase.
Federal Reserve officials typically evaluate several months of inflation, employment and economic growth data before changing policy.
Still, the tone of Waller’s comments suggests that the possibility of higher rates is no longer purely theoretical.
Bottom line
The Federal Reserve is not saying that another rate increase is certain.
It is warning that inflation may force policymakers to keep borrowing costs elevated—or potentially raise them again.
For consumers, that means cheap credit may not return soon. Paying down variable-rate debt, comparing loan offers and moving idle savings into higher-yield accounts could be sensible steps while the outlook remains uncertain.
The next inflation report will help determine whether the Fed’s warning becomes a real policy shift or remains a precautionary message.
None of these situations are unusual, yet many people are forced to rely on credit cards or personal loans simply because they don’t have cash available when they need it most.
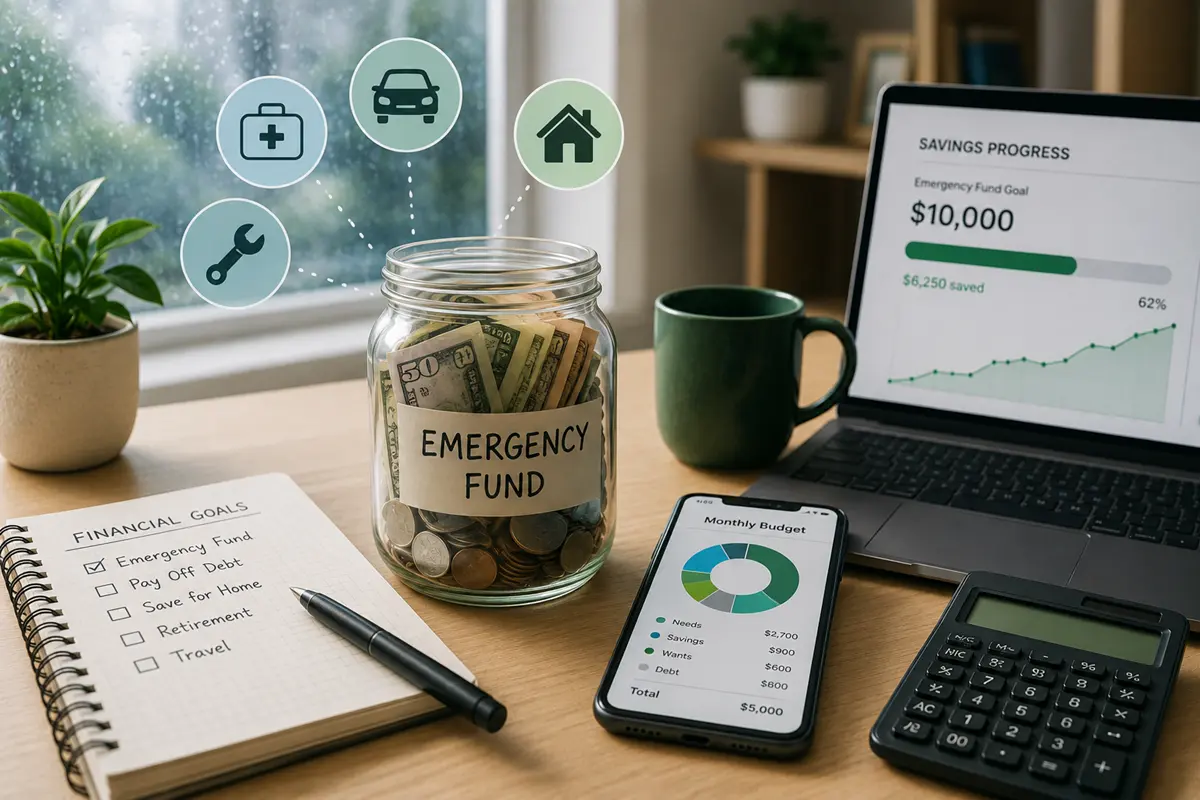
That’s exactly why an emergency fund exists.
An emergency fund isn’t money that’s meant to grow quickly or generate investment returns. Its purpose is much simpler: to protect you from turning unexpected problems into long-term financial setbacks.
Think of it as financial insurance for your everyday life.
If an emergency never happens this month, that’s great. Your savings remain untouched. But when life inevitably throws you a surprise, you’ll be grateful that you planned ahead.
Why everyone needs an emergency fund
Financial emergencies don’t happen because someone is bad with money.
They happen because life is unpredictable.
A sudden expense can affect anyone, regardless of income.
Without emergency savings, many people are forced to:
Use high-interest credit cards
Borrow money from family or friends
Take out expensive personal loans
Delay paying important bills
Withdraw money from retirement accounts
Each of these solutions can create even bigger financial problems later.
An emergency fund helps you avoid making stressful decisions when you’re already under pressure.
What is an emergency fund?
An emergency fund is money set aside specifically for unexpected expenses that cannot reasonably be planned for.
The key word is unexpected.
This isn’t the same as saving for a vacation, buying a new phone, or paying holiday expenses.
Those are planned purchases.
An emergency fund is reserved for situations that threaten your financial stability or your ability to cover essential living expenses.
It should remain untouched until a genuine emergency occurs.
What counts as a financial emergency?
Not every surprise expense qualifies as an emergency.
A good rule is to ask yourself one question:
“Could I have reasonably planned for this?”
If the answer is yes, it probably shouldn’t come from your emergency fund.
Typical emergencies include:
Job loss
Medical expenses
Emergency home repairs
Major car repairs
Urgent travel due to a family emergency
Essential appliance replacement
Unexpected veterinary bills
Expenses that usually don’t qualify include:
Holidays
Shopping
New electronics
Concert tickets
Restaurant visits
Planned home renovations
Seasonal sales
How much should you save?
There’s no single emergency fund amount that works for everyone.
The right size depends on your income, monthly expenses, job stability, and family situation.
Instead of focusing on a specific dollar amount, financial experts usually recommend saving enough to cover several months of essential living expenses.
As a general guideline:
If you are…
Recommended emergency fund
Single with stable income
3 months of expenses
Couple with two incomes
3–4 months
Self-employed or freelancer
6–12 months
Single-income household
6 months or more
Retired
6–12 months
Notice that these recommendations are based on expenses, not income.
If your essential monthly expenses are $3,000, then a six-month emergency fund would be:
$3,000 × 6 = $18,000
That’s your target—not necessarily something you need to save immediately.
Start with a smaller milestone
Many people become discouraged because the final number seems overwhelming.
Instead of aiming for $20,000 right away, break the goal into smaller milestones.
For example:
Milestone
Goal
Starter fund
$500
First safety cushion
$1,000
One month of expenses
$3,000
Three months of expenses
$9,000
Six months of expenses
$18,000
Reaching smaller goals creates momentum and makes saving feel much more achievable.
Where should you keep your emergency fund?
An emergency fund should meet three important requirements.
It should be:
Safe
Easy to access
Separate from your everyday spending account
The purpose isn’t to earn the highest possible return.
The purpose is to have money available when you need it immediately.
Many people choose:
A high-yield savings account
A money market account
A separate bank savings account
A cash management account
Avoid keeping your emergency fund in investments such as stocks or cryptocurrencies.
If the market falls just before you need the money, you could be forced to sell at a loss.
Your emergency fund is about stability—not growth.
How to build your emergency fund faster
Saving thousands of dollars may sound difficult, but small habits often make the biggest difference over time.
Pay yourself first
Treat savings like a monthly bill.
Schedule an automatic transfer to your savings account on payday before you spend anything else.
If you never see the money in your checking account, you’re much less likely to spend it.
Save unexpected income
Bonuses, tax refunds, cashback rewards, or gifts can provide a significant boost to your emergency fund.
Instead of spending the entire amount, consider saving at least part of it.
Cut one unnecessary expense
You don’t need to eliminate everything you enjoy.
Sometimes removing just one recurring expense is enough.
Examples include:
An unused subscription
Premium streaming services
Frequent food delivery
Daily specialty coffee
Impulse online shopping
Even saving $100 per month adds up to $1,200 per year.
Increase your income
Saving isn’t only about spending less.
You can also build your emergency fund faster by earning more.
Ideas include:
Freelancing
Selling unused items
Weekend side jobs
Tutoring
Pet sitting
Ride-sharing
Seasonal work
A temporary increase in income can significantly shorten the time needed to reach your savings goal.
When should you use your emergency fund?
Before withdrawing money, ask yourself three questions.
Is the expense unexpected?
Is it necessary?
Can it wait?
If the answer is yes, yes, and no, your emergency fund is probably the right place to cover the expense.
After using the money, make rebuilding your fund a priority.
Think of it as refilling your financial safety net.
Common mistakes
Investing your emergency fund
Higher returns are attractive, but emergency savings should never depend on market performance.
Saving too little
A few hundred dollars is a great start, but it may not be enough to cover a prolonged emergency.
Keep building your fund even after reaching your first milestone.
Using it for non-emergencies
A vacation discount, a new phone, or holiday shopping might feel urgent, but they aren’t emergencies.
Protect your emergency fund by using it only when it’s truly necessary.
Keeping it in your everyday checking account
If your emergency savings sit next to the money you use every day, you’ll be more tempted to spend them.
A separate account creates a helpful psychological barrier.
Signs your emergency fund is working
You know your emergency fund is doing its job when:
Unexpected bills no longer cause panic.
You rely less on credit cards.
You don’t need to borrow money from friends or family.
Financial setbacks become temporary rather than long-term problems.
You feel more confident making financial decisions.
An emergency fund doesn’t eliminate financial surprises.
It simply gives you the ability to handle them without creating new financial stress.
Frequently asked questions
How much should I have in an emergency fund?
A good goal is to save enough to cover three to six months of essential living expenses. If you’re self-employed or have an unpredictable income, consider building a larger fund that covers six to twelve months.
Is $1,000 enough for an emergency fund?
A $1,000 emergency fund is an excellent first milestone. It can cover many unexpected expenses, such as car repairs or medical bills, but most people should continue saving until they have several months of expenses set aside.
Should I pay off debt before building an emergency fund?
It’s generally wise to save a small emergency fund first, even if you have debt. Having some cash available can prevent you from relying on high-interest credit cards when unexpected expenses arise.
Where is the best place to keep an emergency fund?
A high-yield savings account is one of the best options because it keeps your money safe, easily accessible, and separate from your daily spending account.
Should I invest my emergency fund?
No. Emergency savings should not be invested in assets that can lose value, such as stocks or cryptocurrencies. The primary goal is stability and quick access—not high returns.
Can I use my emergency fund for a vacation?
No. Vacations are planned expenses and should have their own savings goal. An emergency fund should only be used for unexpected and essential financial situations.
How long does it take to build an emergency fund?
That depends on your income and savings rate. Someone saving $300 each month could build a $3,600 emergency fund in one year. The key is consistency rather than speed.
What should I do after using my emergency fund?
Start rebuilding it as soon as your financial situation allows. Replacing the money you used helps ensure you’re prepared for the next unexpected expense.
Bottom line
An emergency fund is one of the simplest—and most valuable—financial tools you can build.
It won’t make you wealthy overnight or generate impressive investment returns. Instead, it gives you something even more important: financial stability when life doesn’t go according to plan.
Whether it’s a medical emergency, an unexpected repair, or a temporary loss of income, having cash set aside allows you to handle the situation without relying on debt or disrupting your long-term financial goals.
The best time to start was yesterday.
The second-best time is today.
Even if you begin with just $25 or $50 per week, consistent saving can grow into a financial cushion that gives you greater confidence, flexibility, and peace of mind.
Most people don’t struggle with budgeting because they’re bad with money.
They struggle because they build budgets that don’t match real life.
A budget that only works on paper quickly falls apart after an unexpected car repair, a birthday party, or a higher-than-usual grocery bill. After missing the target once, many people simply give up and decide budgeting isn’t for them.
The truth is different.
A good monthly budget isn’t about restricting every dollar you spend. It’s about giving every dollar a purpose before you spend it.
Whether you’re trying to pay off debt, save for a vacation, build an emergency fund, or simply stop wondering where your paycheck disappeared every month, a practical budget can completely change your financial habits.
This guide will show you how to build a monthly budget that you can actually stick to.
Why most budgets fail
Many budgeting guides assume life is predictable.
Reality isn’t.
Your electricity bill changes.
Gas prices move.
Friends invite you to dinner.
Children need school supplies.
Your car eventually needs repairs.
Instead of preparing for these situations, many budgets ignore them completely.
The result?
People think they failed.
In reality, the budget failed them.
A successful budget leaves room for flexibility while still keeping your long-term goals on track.
What is a monthly budget?
A monthly budget is simply a spending plan.
It estimates how much money you’ll receive during the month and assigns every dollar to a specific purpose before the month begins.
Your budget should include both fixed expenses, such as rent or mortgage payments, and variable expenses like groceries, transportation, entertainment, and dining out.
It should also include savings.
Many people only save whatever is left over at the end of the month.
Successful savers usually do the opposite.
They treat savings like any other monthly bill.
Step 1: Calculate your monthly income
Start with the amount of money you actually receive—not your salary before taxes.
Include:
Salary after taxes
Freelance income
Bonuses (if consistent)
Rental income
Child support or alimony
Government benefits
Side hustle income
If your income changes every month, calculate the average of the last six to twelve months.
This creates a more realistic number than using your highest paycheck.
Example
Sarah earns:
Income Source
Monthly Amount
Salary
$4,200
Freelance work
$450
Rental income
$350
Total Monthly Income = $5,000
This becomes the starting point for the entire budget.
Step 2: Track every expense
Before changing your spending habits, you need to understand where your money currently goes.
Spend one full month tracking everything.
And yes—everything.
That includes:
Morning coffee
Streaming subscriptions
Online shopping
Parking fees
Food delivery
ATM fees
Tips
Small impulse purchases
Many people discover they’re spending hundreds of dollars every month on purchases they barely remember making.
A budgeting app can help automate this process, but a simple spreadsheet works just as well.
The important part isn’t the tool.
It’s consistency.
Fixed vs Variable expenses
Understanding the difference makes budgeting much easier.
Fixed Expenses
Variable Expenses
Rent
Groceries
Mortgage
Restaurants
Car payment
Fuel
Insurance
Entertainment
Phone bill
Shopping
Internet
Travel
Fixed expenses stay relatively stable.
Variable expenses are where most people have the greatest opportunity to save money.
Step 3: Separate needs from wants
This is often the hardest part of budgeting.
A need is something required to maintain your basic standard of living.
Examples include:
Housing
Utilities
Basic groceries
Transportation to work
Insurance
Healthcare
A want improves your lifestyle but isn’t essential.
Examples include:
Streaming services
Premium gym memberships
Dining out
Designer clothing
New gadgets
Daily coffee shop visits
The goal isn’t to eliminate wants.
It’s to make conscious decisions about them.
Ask yourself three questions
Before making a purchase, ask:
Do I truly need this?
Will I still value it next month?
Is buying this delaying one of my financial goals?
These simple questions can prevent hundreds of dollars in unnecessary spending over the course of a year.
Step 4: Set realistic savings goals
One of the biggest budgeting mistakes is treating savings as an afterthought.
If you wait until the end of the month to save whatever is left, chances are there won’t be much left at all.
Instead, decide how much you want to save before you begin spending. Many people call this strategy “pay yourself first.” The idea is simple: move money into savings as soon as your paycheck arrives, then build the rest of your budget around what’s left.
Your savings goal should be realistic.
Trying to save 40% of your income overnight usually leads to frustration. Saving 5–10% consistently is often more effective than setting an ambitious goal you abandon after one month.
Start with one clear goal
Saving becomes much easier when you know exactly what you’re saving for.
Examples include:
Building an emergency fund
Paying off high-interest debt
Buying a home
Taking a vacation
Replacing your car
Investing for retirement
Instead of creating five different savings goals at once, focus on the one that will have the biggest impact on your finances.
Step 5: Build spending limits for every category
Once you know your income and your priorities, it’s time to decide how much each spending category should receive.
The purpose isn’t to predict every dollar perfectly.
It’s to create reasonable limits that help you make better decisions throughout the month.
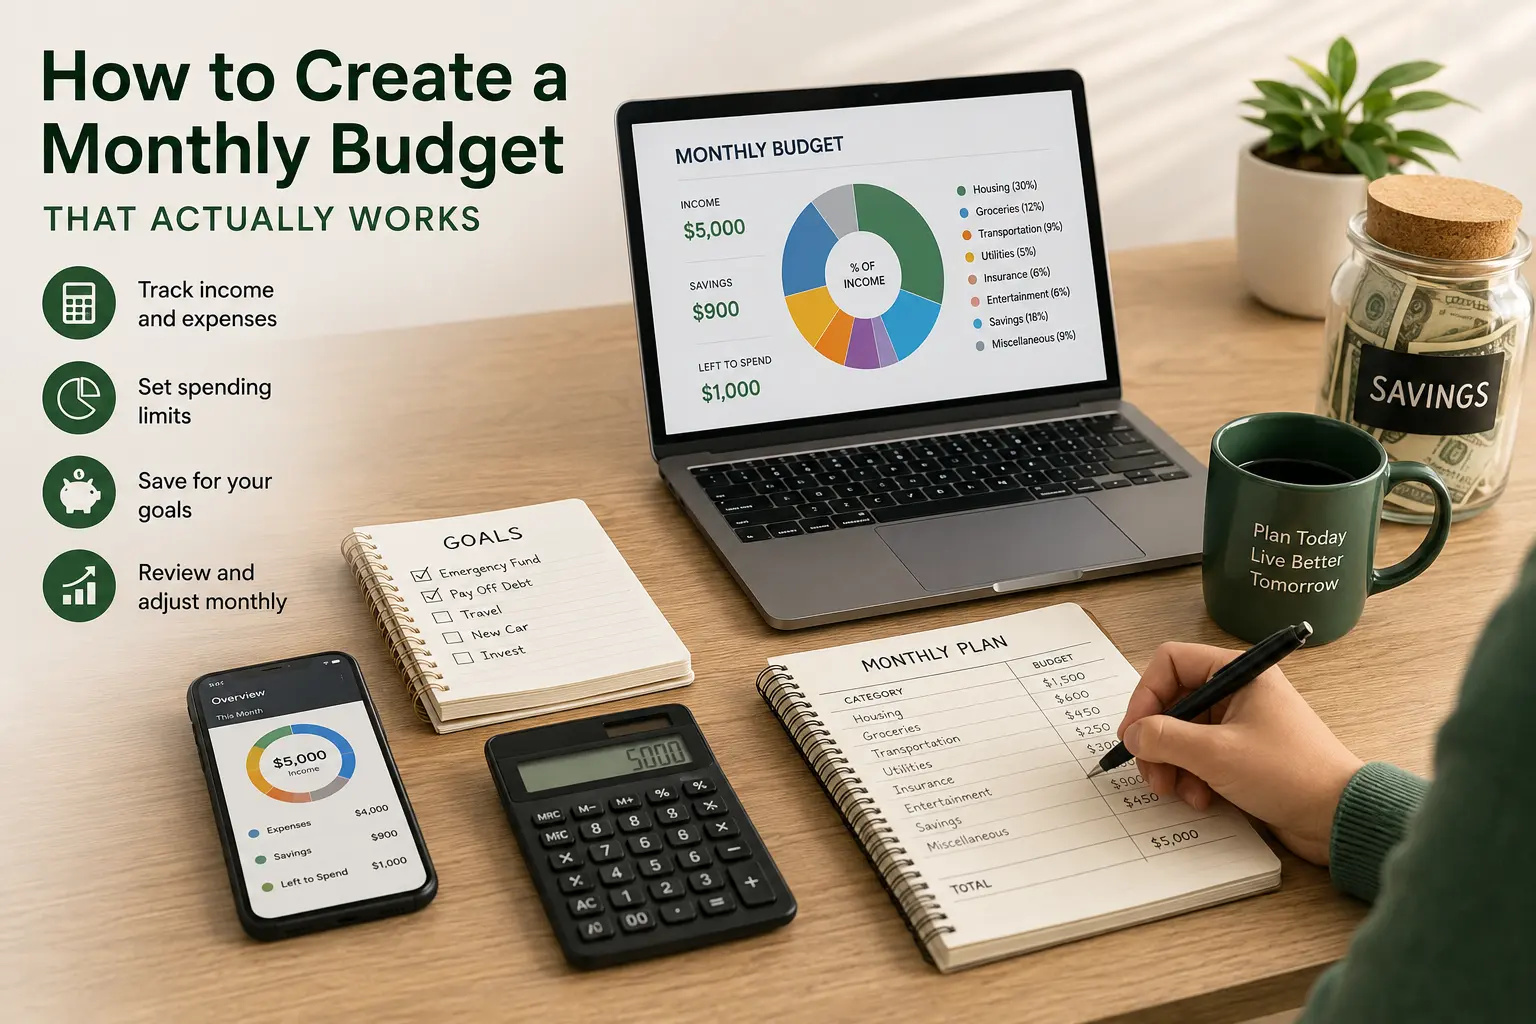
Here’s an example of a monthly budget for someone earning $5,000 after taxes.
Category
Monthly budget
% of income
Housing
$1,500
30%
Utilities
$250
5%
Groceries
$600
12%
Transportation
$450
9%
Insurance
$300
6%
Entertainment
$300
6%
Dining out
$250
5%
Savings & investments
$900
18%
Miscellaneous
$450
9%
Remember that no budget is universal.
Someone living in New York will spend far more on housing than someone living in a smaller city. Families with children will likely spend more on groceries, while someone working remotely may spend much less on transportation.
Your budget should reflect your life, not someone else’s.
Step 6: Review your budget every month
A budget isn’t something you create once and forget.
Life changes.
Your income changes.
Prices change.
Your financial goals change.
Review your budget at the end of every month and ask yourself:
Which categories stayed within budget?
Where did I overspend?
Was that spending necessary?
Can I reduce any expenses next month?
Did I save as much as I planned?
Making small adjustments every month is far easier than trying to completely redesign your budget every year.
Build flexibility into your budget
Unexpected expenses aren’t a matter of if—they’re a matter of when.
Your budget should always include a small buffer for expenses you didn’t anticipate.
This could cover things like:
A birthday gift
A medical bill
Car maintenance
Home repairs
School expenses
Higher utility bills during extreme weather
Without this cushion, even a minor surprise can throw your entire budget off track.
Common budgeting mistakes
Even people who budget regularly make mistakes.
The good news is that most of them are easy to avoid once you recognize them.
Setting unrealistic goals
Cutting your grocery budget in half sounds great on paper.
In reality, you’ll probably exceed it within the first two weeks.
Aim for gradual improvements rather than dramatic changes.
Forgetting annual expenses
Some bills don’t arrive every month.
Examples include:
Car registration
Insurance renewals
Holiday gifts
Property taxes
Annual subscriptions
Divide these costs by twelve and include a monthly amount in your budget.
Ignoring small purchases
A $6 coffee doesn’t seem expensive.
Neither does a $12 lunch.
But daily habits often become the largest source of unnecessary spending over an entire year.
Small purchases deserve just as much attention as large ones.
Giving up after one bad month
Almost nobody follows their budget perfectly.
Overspending once doesn’t mean you’ve failed.
Review what happened, make adjustments, and continue.
Consistency matters much more than perfection.
Signs your budget is working
A successful budget doesn’t necessarily mean you’re spending less.
It means you’re spending with intention.
You know where your money goes.
You’re making progress toward your financial goals.
And you’re no longer surprised by your bank balance at the end of the month.
Some positive signs include:
You’re saving money consistently.
Credit card balances are decreasing.
Unexpected expenses cause less stress.
You feel more confident making financial decisions.
You’re no longer living paycheck to paycheck.
Frequently asked questions
How much of my income should I save each month?
A common recommendation is to save at least 20% of your income, but the right amount depends on your financial situation. If that’s not realistic today, start with 5% or 10% and gradually increase your savings as your income grows or your expenses decrease.
Should I budget if my income changes every month?
Yes. If your income varies, calculate your average monthly income based on the past six to twelve months. Build your budget around that average and prioritize essential expenses before discretionary spending.
What’s the easiest way to track my spending?
You can use a budgeting app, a spreadsheet, or even a notebook. The best system is the one you’ll actually use consistently. Recording your spending every few days is usually easier than trying to remember everything at the end of the month.
How often should I review my budget?
Review your budget at least once a month. However, checking your spending weekly can help you catch problems early and avoid overspending before the month ends.
What if I go over budget?
Going over budget occasionally is normal. Instead of giving up, identify what caused the extra spending and adjust your budget for the following month. Budgeting is an ongoing process, not a one-time event.
Should I pay off debt or save money first?
If you don’t have an emergency fund, try to save a small amount first—often enough to cover one month of essential expenses. After that, focus on paying off high-interest debt while continuing to build your savings over time.
Do I need separate savings accounts?
Not necessarily, but many people find it helpful to keep separate accounts for different goals, such as an emergency fund, vacations, or a down payment. This makes it easier to track progress and reduces the temptation to spend money set aside for future plans.
Can budgeting actually help me build wealth?
Absolutely. Budgeting doesn’t create wealth on its own, but it helps you control cash flow, reduce unnecessary spending, save consistently, and invest regularly. Those habits are the foundation of long-term financial success.
Bottom line
Creating a monthly budget isn’t about restricting your life—it’s about making intentional decisions with your money.
A good budget gives every dollar a purpose, helps you prepare for unexpected expenses, and keeps your financial goals within reach. It won’t be perfect every month, and that’s okay. The goal isn’t perfection – it’s progress.
The most successful budgets are simple enough to follow, flexible enough to adapt to life’s surprises, and realistic enough that you’ll stick with them over the long term.
If you’re just getting started, don’t wait for the perfect moment. Open your bank statements, calculate your income, list your expenses, and build your first budget today. You can always improve it next month.
If you’ve been looking for a better place to keep your savings, you’ve probably come across something called a money market account.
At first glance, it sounds complicated. Some people confuse it with a money market mutual fund, while others assume it’s simply another type of savings account. The truth lies somewhere in between.
A money market account combines features of both checking and savings accounts. It allows your money to remain easily accessible while often paying a higher interest rate than a traditional savings account. For many households, it can be a useful place to store emergency savings or cash that isn’t needed for everyday spending but shouldn’t be invested in the stock market.
Understanding how it works can help you decide whether it deserves a place in your financial plan.
Why money market accounts exist
Banks compete for customer deposits.
One way they attract savers is by offering accounts that pay more interest than standard savings accounts while still providing flexibility.
Money market accounts were designed for people who want to earn interest without locking their money away for months or years.
Unlike certificates of deposit, which usually require you to leave your money untouched until the maturity date, money market accounts generally allow withdrawals whenever you need them, although some institutions may limit certain types of transactions.
This flexibility makes them attractive for short-term financial goals and emergency savings.
How a money market account is different from a savings account
At first glance, the two accounts appear almost identical.
Both earn interest.
Both are typically FDIC-insured when held at participating banks.
Both allow you to deposit and withdraw money.
The biggest differences usually involve interest rates, minimum balance requirements, and account features.
Some money market accounts offer debit cards or limited check-writing privileges, making them slightly more flexible than traditional savings accounts.
Others simply reward customers who maintain higher balances with more competitive annual percentage yields.
The exact features depend on the financial institution.
When a money market account makes sense
Not every dollar should sit in your checking account.
Likewise, not every dollar belongs in long-term investments.
Money that you may need within the next few months—or during an emergency—often benefits from remaining somewhere that’s both accessible and protected.
That’s where money market accounts can fit naturally.
Someone saving for a home down payment within the next year, building an emergency fund, or setting aside money for major home repairs may appreciate the balance between liquidity and interest earnings.
The account isn’t designed to generate extraordinary investment returns.
Its purpose is stability.
Are there any disadvantages?
Like every financial product, money market accounts involve trade-offs.
Some require relatively high minimum balances to qualify for their best interest rates.
Others charge monthly maintenance fees if certain conditions aren’t met.
Interest rates can also change over time as broader economic conditions evolve.
Because of that, today’s highest-paying account may not remain the leader forever.
Comparing fees, minimum balances, and annual percentage yields is often more important than focusing on promotional offers alone.
Choosing the right account
The best money market account isn’t necessarily the one advertising the highest interest rate.
Instead, look for an account that matches your financial habits.
If you’ll need occasional access to the money, convenience matters.
If you’re building long-term savings, fees and interest rates become increasingly important.
And regardless of where you keep your money, ensure the institution provides federal deposit insurance whenever applicable.
Financial products should support your goals—not complicate them.
A place between spending and investing
Many people think every dollar must either be spent immediately or invested for decades.
Money market accounts remind us that there is another category.
Cash that’s waiting.
Waiting for the next opportunity.
Waiting for a home purchase.
Waiting for an unexpected expense.
Waiting for peace of mind.
Choosing the right place for that money can quietly improve your financial life without requiring dramatic changes or complex investment strategies.
Ask almost anyone who’s built financial security, and they’ll tell you that the first $10,000 was the hardest.
Not because it required complicated investment strategies or an unusually high salary, but because it demanded something much more difficult: changing everyday habits. Before you have meaningful savings, every unexpected expense feels like a setback. A car repair, a medical bill, or even replacing a broken appliance can erase months of progress overnight.
That’s why reaching your first five figures in savings is such an important milestone. It represents more than the balance in your account. It proves you’ve developed the habits necessary to build long-term wealth.
The journey isn’t always fast, and it rarely follows a straight line. But with a realistic plan and consistent decisions, saving $10,000 is achievable for far more people than they realize.
Why the first $10,000 feels so difficult
Saving money becomes easier as your financial foundation grows.
When you have little or no savings, every dollar you set aside competes with immediate needs and everyday temptations. At the same time, your money isn’t yet generating meaningful interest, so nearly all of your progress depends on your own contributions.
Once you’ve accumulated a larger balance, the process begins to accelerate. Interest compounds, financial emergencies become less disruptive, and you’re less likely to rely on debt when unexpected expenses arise.
The first $10,000 creates momentum that makes future financial goals feel much more attainable.
Start with a realistic monthly target
Many people begin by asking how they can save $10,000 as quickly as possible.
A better question is how much they can realistically save every month without abandoning the plan after a few weeks.
Consistency almost always beats intensity.
Saving $300 every month for several years will usually produce better results than attempting to save $1,500 for two months before giving up entirely.
The goal should fit your current financial situation, not someone else’s.
Increase income before cutting everything
Budgeting matters, but there is a limit to how much you can reduce spending.
Income, on the other hand, often has far greater potential.
Negotiating a raise, changing jobs, taking freelance work, selling unused items, or creating a small side business may contribute far more toward your first $10,000 than eliminating every small luxury from your life.
Successful savers usually combine both approaches: they spend intentionally while continuously looking for opportunities to earn more.
Automate your savings
One of the simplest ways to build savings is to remove the decision altogether.
Automatic transfers scheduled for payday ensure that saving happens before money is available for discretionary spending.
Over time, automation turns saving from an occasional activity into a routine financial habit.
People rarely miss money they never had the opportunity to spend.
Give your savings a purpose
Saving becomes easier when the goal feels tangible.
Rather than simply trying to reach $10,000, think about what that money represents.
For one household, it may become a fully funded emergency fund.
For another, it could be the beginning of a down payment on a home.
Others may view it as the foundation of their investment portfolio or the financial cushion that allows them to change careers without fear.
Money saved without purpose often gets spent without purpose.
Celebrate progress, not perfection
Financial goals aren’t achieved through perfect months.
Unexpected expenses will happen.
Some months you’ll save less than planned.
Others you may not save at all.
The important part is returning to the plan instead of assuming you’ve failed.
Building wealth is rarely defined by one outstanding decision. It’s usually the result of hundreds of ordinary decisions repeated over many years.
Your first $10,000 isn’t the finish line.
It’s proof that you’ve built habits capable of carrying you much further.
For millions of Americans, payday brings a brief sense of relief.
Bills get paid, the checking account finally looks healthy again, and for a few days it feels like everything is under control. But as the month moves on, that balance slowly disappears. Rent, groceries, insurance, transportation, subscriptions, and everyday purchases quietly consume the paycheck until there’s little—or nothing—left before the next one arrives.
Eventually, the cycle repeats.
Living paycheck to paycheck isn’t always a sign of poor financial decisions. In many cases, it’s the result of rising housing costs, inflation, healthcare expenses, student loans, or wages that haven’t kept pace with the cost of living. People across every income level experience it, including professionals with six-figure salaries.
The problem isn’t necessarily how much money you earn. Often, it’s how little room exists between your income and your monthly obligations.
What does living paycheck to paycheck really mean?
The phrase is frequently misunderstood.
It doesn’t simply mean having a low income. It means depending on your next paycheck to meet your current financial commitments.
If missing one paycheck would immediately make it difficult to pay rent, cover groceries, or keep up with monthly bills, you’re likely living paycheck to paycheck regardless of your salary.
Some households earn $45,000 a year and struggle.
Others earn more than $150,000 and experience exactly the same financial pressure because their expenses have grown alongside their income.
The common factor isn’t income—it’s the absence of financial breathing room.
Why higher income doesn’t always solve the problem
Many people believe a raise will automatically eliminate financial stress.
Sometimes it does.
But many households experience something known as lifestyle inflation. As income grows, spending grows with it. A larger apartment, newer car, more vacations, premium subscriptions, and frequent dining out gradually become part of everyday life.
Before long, the higher paycheck feels just as tight as the previous one.
Without intentional financial planning, increased income often creates a more expensive lifestyle rather than greater financial security.
The hidden cost of constant financial pressure
Living paycheck to paycheck affects far more than your bank account.
It influences daily decisions, career choices, relationships, and even physical health.
Unexpected expenses become emergencies.
Necessary repairs get postponed.
Retirement savings are delayed.
Credit cards become a temporary solution that often develops into long-term debt.
Over time, financial stress can create a cycle that’s difficult to escape because every setback reduces the ability to prepare for the next one.
Small changes can create breathing room
Escaping the paycheck-to-paycheck cycle rarely happens overnight.
For most people, it’s the result of gradually creating more space between income and expenses.
That may involve reducing recurring monthly costs, negotiating insurance premiums, refinancing expensive debt, increasing income through career development or freelance work, or simply becoming more intentional about discretionary spending.
Building even a modest emergency fund can change the entire equation.
Instead of relying on credit cards when something unexpected happens, savings provide time to respond without immediately creating new debt.
Progress usually begins with small improvements rather than dramatic transformations.
Focus on building margin, not perfection
Many budgeting articles encourage people to cut every non-essential expense.
While reducing unnecessary spending can certainly help, sustainable financial progress comes from creating margin—not eliminating everything enjoyable.
A realistic budget should include room for entertainment, hobbies, and occasional treats.
Financial plans fail when they become impossible to live with.
The objective isn’t to build the cheapest possible lifestyle.
It’s to build one that’s financially sustainable.
Financial freedom starts with one extra dollar
One extra dollar left at the end of the month may not seem significant.
But it represents something much more important.
It means your money is beginning to work for you instead of disappearing as quickly as it arrives.
That extra dollar eventually becomes twenty.
Twenty becomes two hundred.
Two hundred becomes the beginning of an emergency fund.
Every financially stable household started somewhere.
Breaking the paycheck-to-paycheck cycle isn’t about becoming rich overnight.
It’s about slowly creating choices where previously there were none.
Financial freedom isn’t built in a single paycheck.
It’s built through hundreds of intentional decisions that gradually give you more control over your future.
One of the simplest concepts in personal finance is also one of the hardest to apply in everyday life.
Most people understand that paying rent is more important than buying a new pair of sneakers. But real financial decisions are rarely that obvious. Is your daily coffee a need or a want? What about high-speed internet when you work from home? Is replacing your five-year-old smartphone a necessity, or simply something you would like to do?
The line between needs and wants has become increasingly blurred, especially as technology, convenience, and lifestyle expectations have evolved. Understanding the difference isn’t about judging how people spend their money. It’s about making sure your spending reflects your priorities rather than your impulses.
Learning to separate essential expenses from discretionary spending is one of the foundations of successful budgeting and long-term financial health.
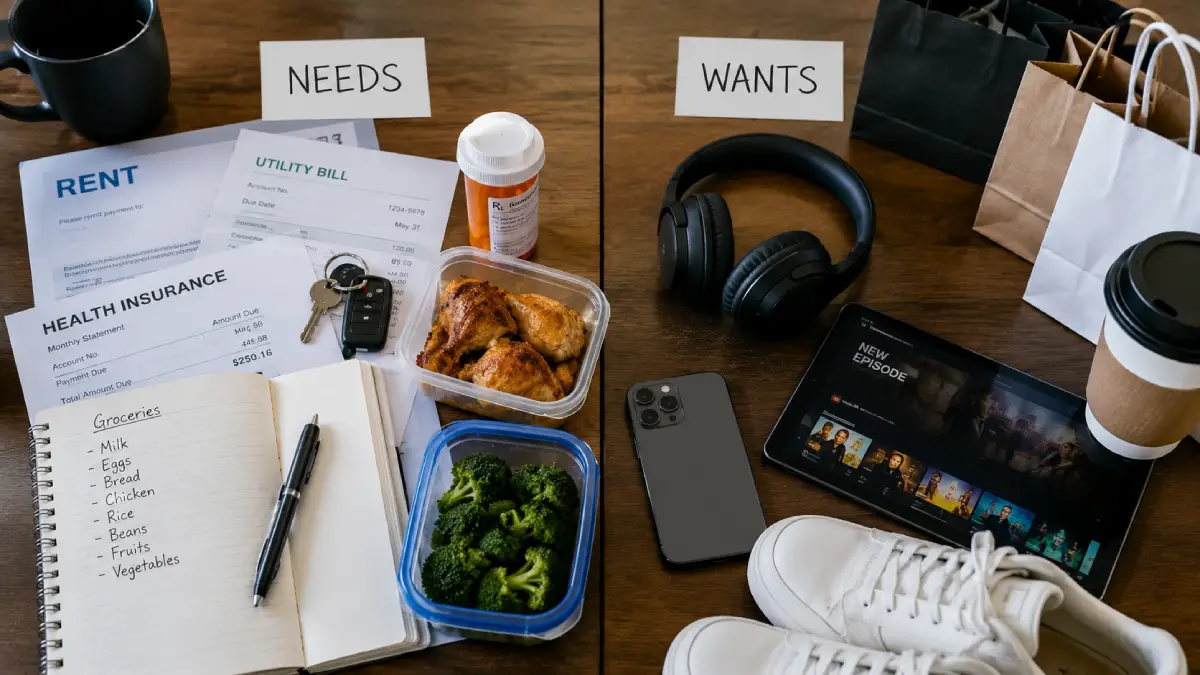
What is a Need?
A need is an expense that supports your basic ability to live, work, and maintain your health and safety.
For most households, that includes housing, groceries, utilities, health insurance, transportation to work, prescription medications, and minimum debt payments. These are the costs that continue regardless of whether you’re trying to save money or reduce spending.
Without them, daily life becomes difficult or impossible.
That doesn’t mean every version of these expenses is a necessity. Owning a car may be essential if public transportation isn’t available, but choosing a luxury vehicle instead of a reliable used car is a lifestyle decision.
The category often stays the same, even when the amount you spend changes dramatically.
What Is a want?
A want is anything that improves your lifestyle without being essential for meeting your basic needs.
Dining out, entertainment subscriptions, vacations, designer clothing, gaming consoles, premium smartphones, and impulse purchases all fall into this category for most people.
Wants aren’t bad.
In fact, eliminating every enjoyable expense usually creates frustration and makes budgets impossible to maintain.
The goal isn’t to stop spending on things you enjoy. The goal is to make sure those purchases happen intentionally and fit comfortably within your financial plan.
Healthy personal finance leaves room for both responsibility and enjoyment.
Why the difference matters
Many financial problems don’t begin with one large purchase.
They develop through dozens of small decisions that feel insignificant on their own.
A streaming subscription here.
Food delivery twice a week.
An upgraded phone plan.
Several online impulse purchases.
Individually, each expense may seem manageable. Together, they can quietly consume hundreds of dollars every month.
Recognizing the difference between needs and wants helps you identify where adjustments can be made without sacrificing your quality of life.
Your priorities will change over time
One of the biggest mistakes people make is believing their budget should remain the same forever.
Financial priorities naturally evolve.
Someone in their twenties may choose to spend more on travel and experiences.
Parents may prioritize childcare, education, and family expenses.
Later in life, retirement savings and healthcare become increasingly important.
What qualifies as a priority changes as life changes.
A good budget evolves with you instead of forcing you into the same spending habits year after year.
How to make better spending decisions
Before making a purchase, ask yourself a few simple questions.
Would my life become significantly more difficult if I didn’t buy this?
Can this purchase wait until next month?
Will I still value this purchase six months from now?
Would I rather have this item or move closer to one of my financial goals?
Those questions often provide more useful answers than simply asking whether something is affordable.
Being able to afford something doesn’t automatically mean it’s the best use of your money.
Financial freedom comes from intentional choices
The difference between people who consistently build wealth and those who constantly feel financially stretched isn’t always income.
It’s often awareness.
People who understand where their money goes tend to make better long-term decisions because they’re spending according to their priorities instead of reacting to every temptation.
Separating needs from wants doesn’t remove enjoyment from life.
It simply ensures that today’s spending doesn’t prevent tomorrow’s opportunities.
Financial freedom isn’t built by saying “no” to everything.
It’s built by saying “yes” to the things that matter most.
Budgeting doesn’t fail because people don’t earn enough money.
More often, it fails because every paycheck arrives without a clear plan.
Money comes in, bills get paid, a few unexpected purchases appear, and by the end of the month many people are left wondering where the rest went. Even households with comfortable incomes can experience this cycle because spending naturally expands to fill whatever money is available.
Zero-based budgeting approaches the problem differently.
Instead of asking where your money went after you’ve spent it, this method asks you to decide where every dollar will go before the month even begins.
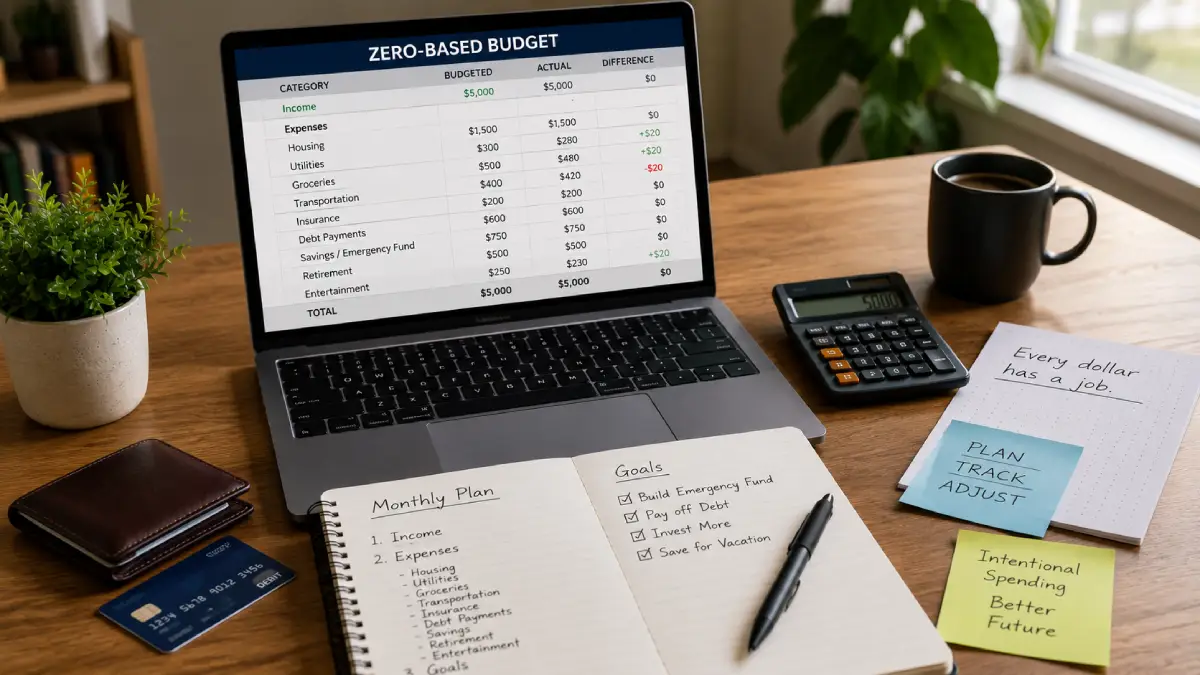
The goal isn’t to spend every dollar. The goal is to give every dollar a purpose.
Whether that purpose is paying rent, buying groceries, investing for retirement, or building an emergency fund, every dollar is assigned a job before it leaves your account.
What does “Zero-Based” actually mean?
The name often confuses people.
It doesn’t mean your bank account should reach zero.
It means that after you’ve assigned your monthly income to spending, saving, investing, and debt repayment, there shouldn’t be any dollars left without a purpose.
If your monthly take-home pay is $5,000, your budget should explain exactly what all $5,000 will do.
Some will pay for housing.
Some will cover transportation.
Some will build savings.
Some will fund entertainment.
Some will reduce debt.
When every dollar has a destination, unplanned spending becomes much easier to recognize and control.
Why this method works
One of the biggest advantages of zero-based budgeting is awareness.
Many people think they have a spending problem when, in reality, they have a planning problem.
Without a clear plan, small purchases rarely feel significant. A coffee here, lunch there, another streaming subscription, a few online orders—they seem harmless individually but often consume hundreds of dollars each month.
Zero-based budgeting makes those decisions visible before they happen.
Instead of reacting to spending, you’re directing it.
That shift in mindset is often more valuable than the budgeting system itself.
It’s About Priorities, Not Restrictions
Critics sometimes argue that zero-based budgeting is too strict.
In practice, it can actually create more freedom.
Nothing prevents you from budgeting for vacations, concerts, hobbies, or weekly dinners with friends. Those expenses simply become intentional rather than impulsive.
Financial guilt often comes from spending money that wasn’t planned.
When entertainment is already included in your budget, you can enjoy it without wondering whether you’re sacrificing more important goals.
A budget should support your lifestyle—not eliminate it.
The biggest mistake beginners make
Many first-time budgeters spend hours creating the perfect spreadsheet, only to ignore it after two weeks.
The problem isn’t usually the budget itself.
It’s expecting life to follow the plan perfectly.
Unexpected expenses happen.
Cars need repairs.
Medical bills arrive.
Birthdays appear.
Travel plans change.
A successful zero-based budget includes flexibility. Small adjustments throughout the month aren’t signs of failure—they’re signs that you’re managing real life instead of following a rigid template.
Is Zero-Based budgeting right for everyone?
Like every budgeting method, zero-based budgeting has strengths and weaknesses.
People with regular monthly income often find it easy to implement because they know approximately how much money they’ll have available each month.
Freelancers, commission-based employees, and business owners with fluctuating income may need a more flexible version based on conservative income estimates.
The underlying principle, however, remains valuable for almost everyone: intentional spending leads to better financial decisions.
Planning every dollar builds better habits
The greatest benefit of zero-based budgeting isn’t mathematical.
It’s psychological.
Once people begin assigning purpose to every dollar, they often become more thoughtful about every financial decision they make.
Saving becomes automatic.
Impulse purchases become easier to recognize.
Financial goals become more visible.
And perhaps most importantly, money begins to feel like a tool rather than something that constantly disappears without explanation.
Budgeting isn’t about perfection.
It’s about making sure your money reflects your priorities instead of your habits.
Most people don’t fail at budgeting because they’re bad with numbers.
They fail because they create budgets they were never going to follow.
A spreadsheet that leaves no room for dining out, birthdays, vacations, or unexpected expenses might look perfect on paper, but it usually falls apart within weeks. When that happens, many people assume budgeting simply isn’t for them.
The truth is very different.
A good budget isn’t about restricting your life. It’s about giving every dollar a purpose while leaving enough flexibility to handle real life. The most successful budgets aren’t necessarily the most detailed—they’re the ones people can maintain month after month.
Whether you’re trying to stop living paycheck to paycheck, build an emergency fund, or simply understand where your money goes each month, creating a realistic budget is one of the most valuable financial habits you can develop.
Start by understanding your income
Every budget begins with one number: the amount of money that actually reaches your bank account.
For employees, this usually means your take-home pay after taxes, retirement contributions, health insurance, and other deductions.
If you’re self-employed or your income changes from month to month, calculate an average based on the last six to twelve months rather than your highest-earning month. Budgeting around unusually high income often leads to overspending during slower periods.
Your budget should be built around money you already have—not money you hope to earn.
Find out where your money is really going
Before deciding how much you should spend, it’s important to understand how you’ve been spending.
Review your last two or three months of bank and credit card statements. Most people discover at least one surprise. It might be recurring subscriptions they forgot about, frequent restaurant visits, or dozens of small purchases that never felt significant individually but add up quickly over time.
Patterns matter more than isolated expenses.
Once you understand your spending habits, you’ll be able to make informed decisions instead of guessing where your money disappears every month.
Separate needs from lifestyle choices
One of the biggest challenges in budgeting is distinguishing between expenses that are essential and those that are optional.
Housing, utilities, groceries, insurance, transportation, and minimum debt payments generally fall into the “needs” category.
Streaming services, premium subscriptions, dining out, entertainment, shopping, and vacations are typically discretionary expenses.
This doesn’t mean discretionary spending is bad.
A sustainable budget should include money for enjoying life. Eliminating every enjoyable expense often creates frustration that leads people to abandon their budgets altogether.
The goal is balance, not perfection.
Give every dollar a job
Many financial planners recommend assigning every dollar of income to a purpose before the month begins.
Some money pays bills.
Some builds savings.
Some goes toward investing.
Some covers entertainment.
When income has a clear destination, it’s much easier to avoid wondering where your paycheck disappeared.
Budgeting isn’t about tracking money after it’s gone. It’s about deciding where it should go before you spend it.
Expect the unexpected
Life rarely follows a perfect monthly schedule.
Car repairs, medical bills, school expenses, holiday shopping, home maintenance, and annual insurance premiums all appear eventually.
Instead of treating these as financial emergencies, build room for them into your budget.
Setting aside even a small amount each month for irregular expenses can prevent them from disrupting your finances later.
This is one reason many households combine budgeting with an emergency fund, creating an additional layer of financial protection when unexpected costs arise.
Review your budget every month
A budget isn’t something you create once and never revisit.
Income changes.
Expenses increase.
Goals evolve.
Reviewing your budget once a month allows you to adjust before small problems become larger ones. Maybe your rent increased, your insurance premium changed, or you’ve recently paid off a loan. Each of those events creates an opportunity to reassign money toward new priorities.
Financial planning works best when it evolves alongside your life.
The best budget is the one you’ll actually follow
There’s no universally perfect budgeting system.
Some people prefer the simplicity of the 50/30/20 budget rule. Others like zero-based budgeting or detailed spending categories. Many households combine several different approaches over time.
The best budget is the one that helps you spend intentionally without making everyday life feel unnecessarily restrictive.
Consistency almost always beats complexity.
Even a simple budget followed for five years will usually produce better results than an elaborate financial plan abandoned after one month.
Creating a budget isn’t about controlling every dollar. It’s about giving yourself the confidence that your money is moving you closer to the life you want.